Appraisal records confirm 225 homes and a substantial tax base. The remaining question is whether SEDC documented every requirement behind its $625,000 incentive.
SEAGOVILLE — A $625,000 entry in Seagoville’s economic-development budget traces to a development agreement involving apartments, retail space and sewer infrastructure near U.S. Highway 175 and Malloy Bridge Road.
A separate SEDC financial report goes beyond the budget projection: its December 31, 2024 statement of activities records $625,000 in actual year-to-date expense for the KRR incentive.
The accompanying explanation identifies the project as KRR Infrastructure Improvement.
That establishes a reported public expense. It does not, by itself, establish compliance with every construction, investment, ownership and operating condition.
The proposed fiscal 2026 budget places the $625,000 in both the fiscal 2025 budget and projected-spending columns. The proposed fiscal 2026 column contains no additional KRR allocation.
Readers should not interpret those repeated figures as separate $625,000 awards. The SEDC is supported by a half-cent local sales tax.
The city’s fiscal 2025 financial report lists KRR Malloy Bridge Residential as Seagoville’s largest property taxpayer by taxable assessed value: $58,799,910, or 4.07% of the city’s taxable value.
It exceeds the $55,229,412 listed for O’Reilly Auto Enterprises. Those figures appear in the report’s unaudited statistical section.
More recent Dallas Central Appraisal District information lists the residential parcel’s 2026 certified value at $46,473,550, about 21% below the figure in the city’s 2025 table. The comparison does not establish why the figures changed.
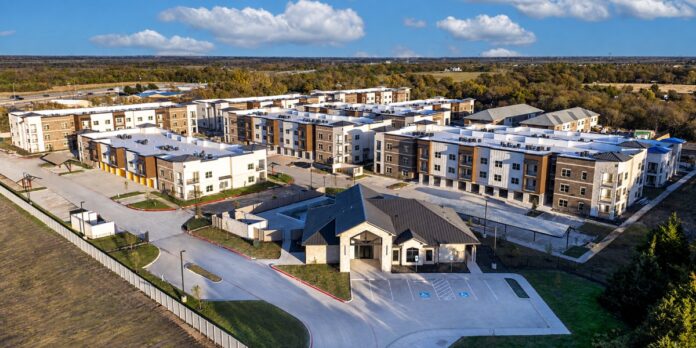
The appraisal account identifies 14.641 acres in the Joseph Kemp Replat, 225 units and a 2024 construction year. It lists KRR Malloy Bridge Residential LLC as owner.
The page labels its current ownership and improvement fields “Current 2027,” while separately identifying its valuation as “2026 Certified Values.”
DCAD estimates Seagoville city taxes on the parcel at $334,954.86 and lists no exemptions. That estimate is not proof of taxes collected. Nor does the property’s value establish the incentive’s net return without considering city service costs, prior land value and other public assistance.
The December 2024 SEDC cash analysis separately reports $625,000 in economic-development project outflows during the first three months of fiscal 2025. Alongside the named KRR expense, this supports a reported cash disbursement, rather than merely a budget reservation.
The records reviewed do not identify the exact payment date, check recipient or invoices approved for reimbursement.
The original agreement presented to the council in July 2021 named KRR Malloy Bridge Residential LLC and KRR Malloy Bridge Retail LLC as the developers.
It described approximately 22.17 acres at the southeast corner of Highway 175 and Malloy Bridge Road, with 40,000 square feet of retail space, 225 apartments and townhomes, and an off-site sewer line intended for city dedication and additional business connections.
The original version contemplated a lump-sum grant within 75 days of execution. A later amendment materially changed the arrangement.
The November 2022 council packet’s amended agreement provides:
| Obligation | Terms |
|---|---|
| Public funding | Up to $625,000, reimbursing verified infrastructure expenses. |
| Sewer | A 10–12-inch line beneath Highway 175, with 24-inch encasement and connections for existing and future development. |
| Housing | 213 apartments and 12 townhomes. |
| Retail | At least 48,460 square feet of Super 1 Foods space. |
| Property | 22.155 acres: 6.926 for Brookshire, 14.641 for multifamily, 0.588 for landscaping. |
| Investment | At least $25 million for infrastructure and multifamily; at least $625,000 for infrastructure. |
| Deadlines | Construction begins within one year of execution; infrastructure, housing and retail completed within five years. |
| Dedication | Infrastructure and necessary access rights transferred to the city within 60 days of completion. |
The amendment identifies Joseph Kemp as manager of both KRR entities. It requires proof of financing and recorded deeds, including the grocery-property sale to Brookshire, before funding.
No numerical job-creation minimum appears in the amended agreement reviewed.
Specified breaches, following termination, trigger repayment of 100%, 50% or 25% of the grant. Infrastructure spending below $625,000 requires repayment of the difference.
The packet’s signature dates are blank. Its deadline rules therefore cannot establish exact calendar due dates.
State construction records identify KRR Malloy Bridge Residential LLC as the listed owner of the residential project at 108 South U.S. Highway 175, with Joseph Kemp as its contact. The filing reports a $40 million estimated cost and now carries a Project Closed status.
Those details are useful evidence about the development. The estimate is not proof of the final qualifying investment, and closing an accessibility-program record does not certify compliance with an SEDC incentive agreement.
Malloy Bridge’s own website advertises apartments and townhomes at 108 U.S. Highway 175 Frontage Road, with applications, tours and a resident portal. That supplies direct operating evidence, although it cannot establish the final occupancy approvals for every unit.
Super 1 Foods’ own website lists its Seagoville store at 125 Hall Road, providing evidence of an operating grocery business. That listing does not independently verify the contractual floor area, recorded ownership or compliance throughout the required operating period.
The records reviewed did not include the executed amended agreement, reimbursement invoices, city acceptance and dedication documents, final occupancy certificates for the entire residential development, or a comprehensive SEDC compliance determination.
Appraisal records establish the listed residential owner, but the current grocery deed and the ultimate ownership of the KRR companies were not independently established.
This review did not obtain responses from SEDC, KRR or Brookshire. Missing documents in the material reviewed should not be treated as proof that those documents do not exist.
Consequently, this review cannot conclude that every requirement was met. It also does not establish a breach or wrongdoing.
The central accountability question remains whether SEDC’s supporting records document the qualifying costs and each promised public benefit—not simply whether the $625,000 appears in its accounts.